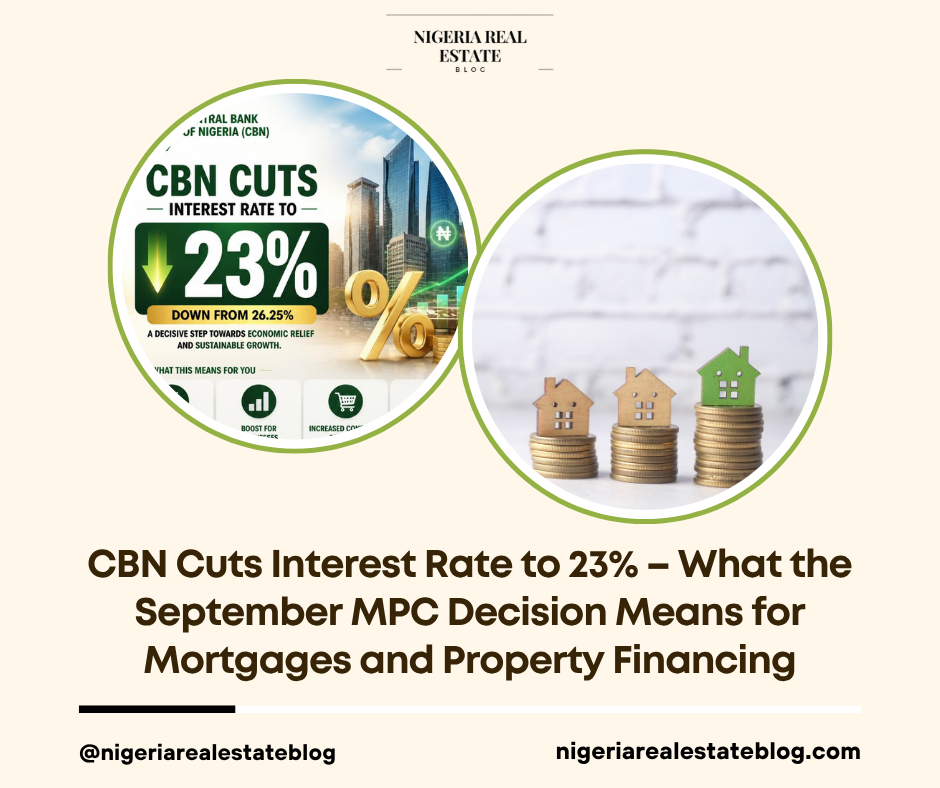
The Central Bank of Nigeria (CBN) has reduced the Monetary Policy Rate (MPR) to 23% following its September 2026 Monetary Policy Committee (MPC) meeting. This marks a further step in the gradual easing cycle and is being closely watched by developers, mortgage lenders, and prospective homebuyers.
While the cut is positive in direction, its actual impact on real estate financing will depend on how quickly commercial banks and mortgage institutions adjust their lending rates.
What the Rate Cut Means
The MPR serves as the benchmark that influences the cost of funds in the banking system. A reduction generally signals lower borrowing costs over time, but the transmission to end-user mortgage and developer loan rates is rarely immediate or one-for-one.
Key points to note:
- Commercial mortgage rates are still expected to remain significantly higher than the MPR.
- The speed and extent of any reduction in lending rates will vary across banks.
- Government-backed schemes (such as NHF and other concessionary products) operate under different pricing structures and may not move in lockstep with the MPR.
Potential Impact on Different Stakeholders
Homebuyers
- A lower MPR improves the medium-term outlook for mortgage affordability.
- Buyers currently servicing or considering commercial mortgages may see some relief if banks pass on part of the reduction.
- Those relying on NHF or other subsidised schemes are less directly affected by this particular cut.
Developers
- Lower funding costs can improve project viability, especially for developments that rely on bank financing.
- The impact will be more meaningful for developers with existing floating-rate facilities or those planning new debt-funded projects.
- Equity and alternative funding structures will remain important given that commercial rates are still elevated in absolute terms.
Investors and Landlords
- Improved financing conditions can support transaction volumes over time.
- Rental demand fundamentals remain the primary driver of investment performance in the near term.
Realistic Expectations
It is important to maintain perspective:
- A move to 23% is helpful but does not return the market to a low-interest-rate environment.
- Full transmission of the cut into lower mortgage rates may take several weeks or months.
- Other factors — including inflation trends, naira stability, and banks’ risk appetite — will continue to influence actual lending rates.
What Buyers and Developers Should Do Now
- Monitor announcements from major mortgage lenders and commercial banks regarding rate adjustments.
- Revisit existing loan offers or term sheets, as some institutions may review pricing.
- Continue prioritising strong cash-flow buffers and realistic affordability assessments.
- For new projects, stress-test financing assumptions under both current and moderately lower rate scenarios.
Final Thoughts
The CBN’s decision to cut the benchmark rate to 23% in September 2026 is a constructive signal for the real estate sector. It supports a gradual improvement in financing conditions, though the benefits will likely materialise progressively rather than overnight.
Buyers, developers, and investors who stay informed and maintain disciplined financial planning will be best positioned to take advantage of any easing that follows.
How do you expect this rate cut to affect your property or financing plans? Share your thoughts in the comments.
Join Over 11,000 Real Estate Enthusiasts!
Stay ahead with our quick 5-minute roundup of Nigerian and global real estate updates, delivered to your inbox every weekday. Don’t miss out on insider tips, market trends, and exclusive insights!